Market Ethos
19 October 2026
Tracking the AI buildout
Sign up here to receive the Market Ethos by email.
This isn’t our first bubble. In fact, we have invested through many bubbles from dotcom, energy trading, China (2x), commodities, housing, mobile, fracking, cloud, marijuana, and now AI. Each was different in its trajectory, speed, size, inflation, and deflation. Some bubbles are big but narrowly focused (dotcom), some are gradual that have systematic ramifications (housing), and some grow and pop with limited economic consequences (marijuana). This AI one is already REALLY BIG and PERVASIVE; so big that its path will likely be the dominant factor in driving equity and bond markets plus the global economy in the coming years.
The AI infrastructure buildout has some pretty mind-blowing numbers behind it. Based on current forecasts, this is bigger than any of the big infrastructure spends over the past few hundred years. Measuring the spend vs the size of the economy, the only past infrastructure spend that comes close was the railway expansion back in the late 1800s. We will see, as the railway buildout lasted two decades and the AI infrastructure spend is only a few years old now.
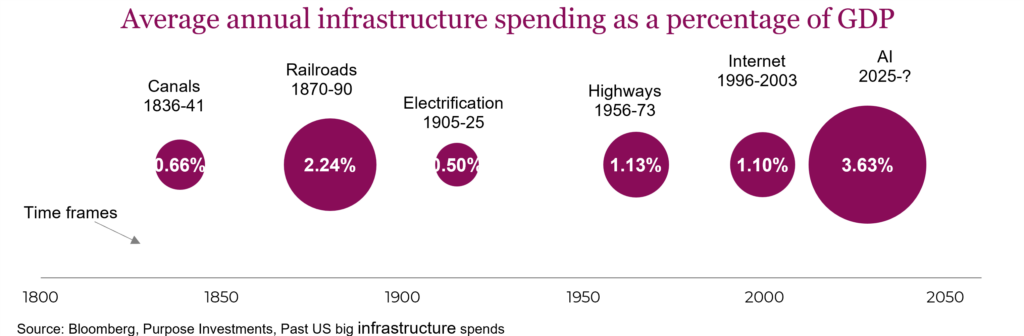
A very important caveat for the above chart, which certainly encourages enthusiasm for this bubble, is the path of investment returns. The railway bubble lasted 20 years but railway investors enjoyed strong returns in the 1870s and very poor results in the 1880s even as the infrastructure spend and buildout persisted. Same with the internet; 2000 to 2003 was abysmal for stocks but cable continued to be laid. For a sports analogy, you don’t want to stick around till the end of the game, in fact you may want to leave at halftime. Our guess (given expectations are high and still rising, while company sizes are already massive), we are in the first half of the buildout but the stock market may be at the second hydration break.
The AI infrastructure buildout is real, with lots of capital and little concern over rising costs as leadership or ‘being there’ is paramount. And it is not just the mega data centre projects, as we may all have a DGX Spark in our garage in a few years. Will there be a positive ROI (return on investment) for all this infrastructure? Perhaps —the demand continues to build as do the use cases. Add shortages or tight supply of memory, chips, power tie-ins, or simply a shortage of compute, and the enthusiasm is easy to justify. Conversely, some have already modelled that the global economy may have to spend more on AI compute than food to justify what is forecast to be built out. Or the labs will make more compute efficiency gains. Open models vs closed, integrated customer solutions vs stand-alone offerings. Sticking with our game analogy, there are a lot of twists and turns ahead.
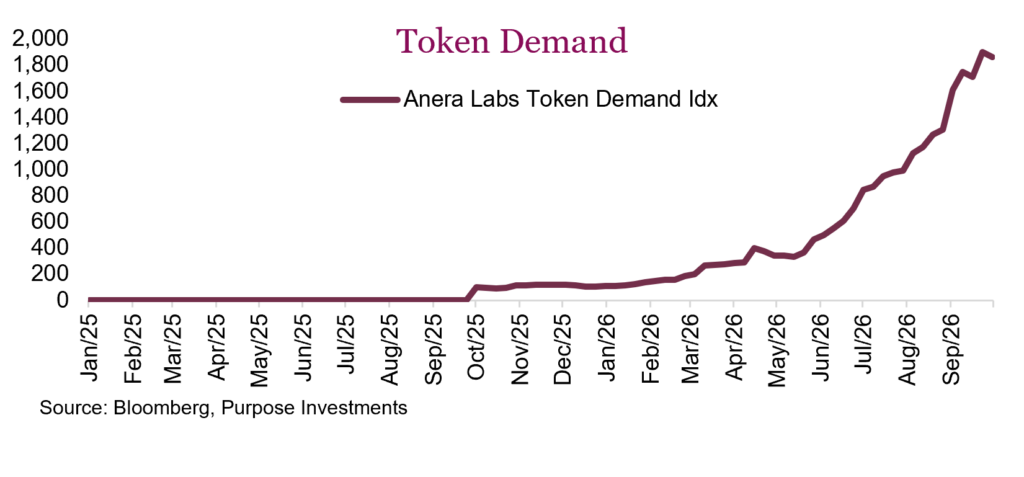
Regardless of your views on the next leg of this bubble and the market/economic implications, you are exposed. This is an everywhere bubble, evident in chips, memory, optics, storage and LLM providers. Now it has spread to lift shares in many industrials involved in building or power to even boring utilities. Or from a geographic perspective, pick an equity market and there is often a good amount of AI exposure. The U.S. equity market leads this, thanks to many of the megacaps and model providers. The top 10 weighted names in the S&P 500, totaling over 40% of the index, are all AI plays. Emerging markets and Japan have a lot of exposure on the tech hardware side, including memory and chips.
Even if you have limited AI exposure on the equity side of the portfolio, you may be getting some on the bond side. The investment grade fixed-income universe in the U.S. used to be about 7-8% weighted to the megacap AI names and providers of the picks and shovels or chips and connectivity. That weight started to rise a year ago and now sits at 12.1%. The biggest increases came from Alphabet, Amazon, Meta, SpaceX and Oracle.
Even if you don’t own many direct AI-related bonds or many direct AI-related equities, you are still exposed. This rapid bond issuance is one of the contributors to rising bond yields everywhere. Yes, this is such a big deal it is influencing government bond yields because of competition for capital. And the capex spending, much of it devoted to building data centers to drive AI compute and training, is helping supercharge economic growth.
There is no easy way to accurately measure this economic impact, but it is noticeable. We isolated two sub-components of U.S. GDP that would be largely impacted by the data centre spend, namely fixed investment in information processing and intellectual property spending. Over the past 30 years, these two have averaged about a +0.4% contribution to real GDP but currently are running at almost 1.0%. With AI-related capex accelerating in 2025 and in 2026, the impact is becoming very noticeable even in the headline GDP numbers.
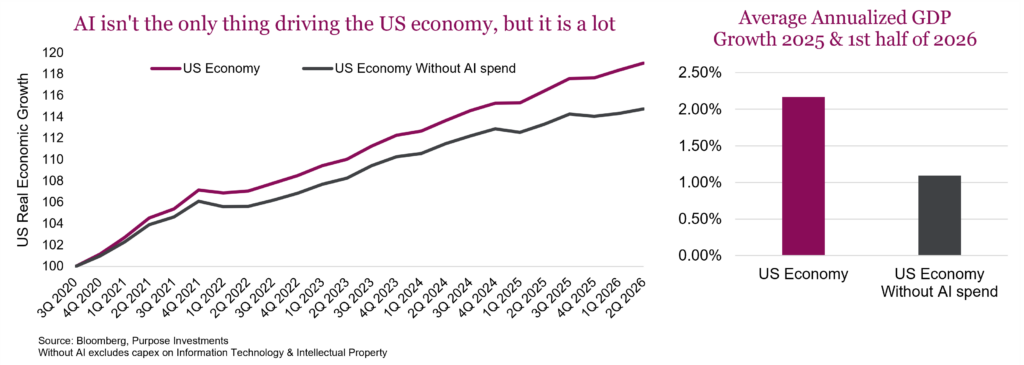
For some context, this capex tech spending did spike in 2021 as remote or hybrid work required infrastructure spending. That was short lived. This tech spending was also big in late 1990s and that lasted for 3-4 years as the internet was built. Without this spending, the U.S. economy would certainly be growing at a slower pace. If it were to slow or even normalize, headline growth would take a hit. And this may cause other areas of economic weakness to become more apparent, such as struggling housing or the bifurcated consumer.
And if you don’t own many AI-related stocks or bonds or exposure to U.S. economy, you are still exposed. A good portion of this capex is spent on imports, which is helping economic growth in many other countries around the world.
AI has become a dominant factor in many equity markets around the world, and now it is driving bond yields plus boosting economic growth. AI is everywhere and everything.
Constructive on AI
Within our portfolios we have AI exposure, at a level we believe as reasonable. The technology is awesome and use cases continue to expand. It is a bubble, though fortunately we appear to still be in the ‘inflation’ stage. Given AI’s heft, there will likely be a number of oscillations in AI excitement, leading to oscillations in the market. This could persist for many quarters or even years, which brings us to how to watch for signs the bubble is at risk. We are not overly confident as history teaches us it will likely be something that surprises us all, but we do have a number of things we are focused on:
Earnings & expectations – The dotcom bubble didn’t end because pets.com launched, it just coincided with it. With hindsight, it was really that expectations grew so high that when the numbers, which were still growing nicely, couldn’t keep up with the hype, the market caps became unsustainable. For now, though, earnings have continued to deliver.
Economy & yields – This kind of spending is not overly sensitive to higher costs of capital, aka higher yields. But these higher yields are taking a toll on the overall economy. Should this drag begin to overwhelm the growth impulse from the capex spend, a cooling economy could easily start bubble deflation.
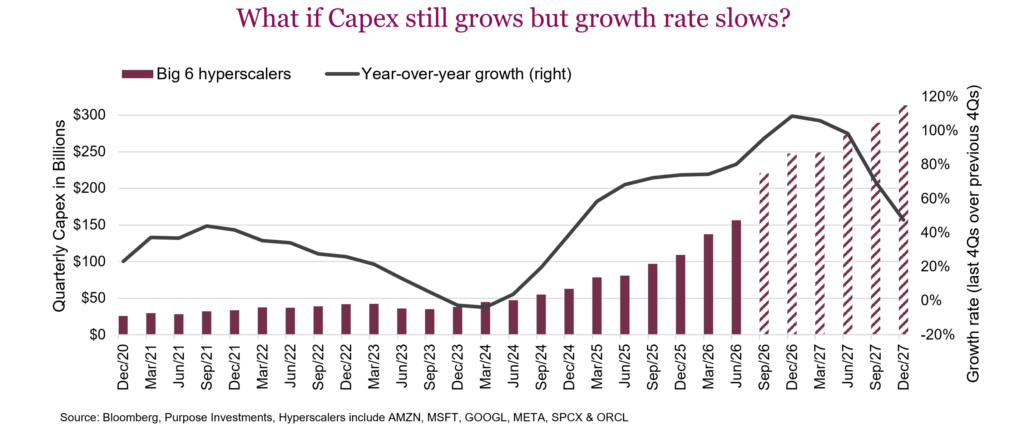
Decelerating growth – Markets react much more to the second derivative: changes in acceleration vs growth. Hyperscaler capex was $365B in 2025, more than doubling to $762B in 2026 based on reported and forecasts. 2027 forecasts are for continued growth to $1,125B but that implies the growth pace falling from 108% to 47%. Of course, forecasts can change but that could easily cause bubble deflation. Even though things are growing, the rate of change matters a lot.
Capital access – With the bond market being tapped from many issuers, higher yields being required is a sign of investor sceptics. Keep an eye on credit default swaps (CDS) for big AI-related issuers. There is now CDSs for Alphabet, which didn’t used to exist, while Oracle has theirs priced at 2.7%. The equity market’s ability to absorb future mega IPOs will also be a sign. So far so good though.
Final thoughts
This is a bubble that is big enough and pervasive enough that it will impact markets and economy. We are all in it now and we believe the key to navigating it will be to monitor its path. Be aware of your exposures, be opportunistic and be prudent by ensuring your portfolio has adequate diversification offsets.