Today
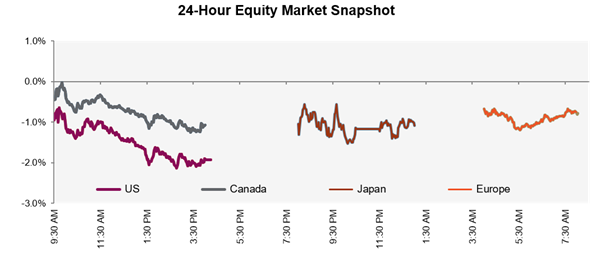
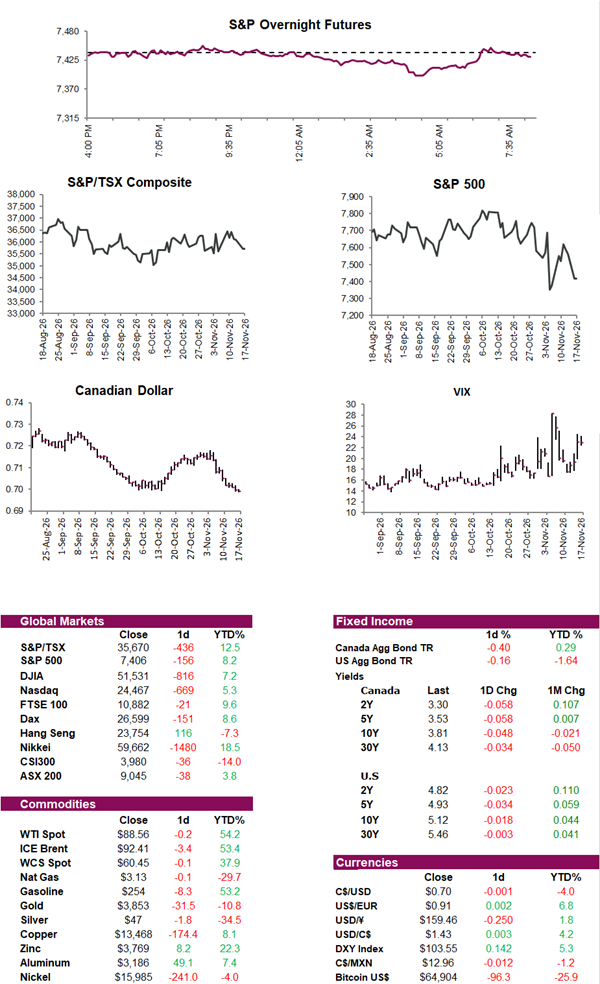
Stocks are pointing mostly lower this morning, with Nasdaq futures seesawing ahead of Nvidia’s highly anticipated earnings after the close. Investors will first digest October U.S. retail sales released this morning, which rose 0.2% versus expectations of +0.1%, following September’s +0.8% gain. Excluding autos, sales rose 0.6% versus expectations of +0.4%, following September’s +0.9% gain. Later today, Nvidia will report its first results since Jensen Huang’s departure. Investors expect another strong quarter, but the real test will be what comes next under interim CEO Colette Kress. Beyond whether guidance differs from forecasts issued under Huang, investors will be watching for signs that resistance to data centre development is weighing on chip demand and whether Nvidia intends to maintain its financial backing of customers. New U.S. restrictions targeting China’s access to advanced AI chips through countries such as Singapore, Malaysia and Thailand add another complication to the growth outlook (more on that below). The stakes are high following a bruising session for equities yesterday, with the Nasdaq falling -2.5%, the S&P 500 -1.9% and the TSX -1.0%, while selling pressure carried into European and Asian markets. In Japan, SoftBank fell another -4%, bringing its decline from its June peak to ~62%. Its stake in chip designer Arm has added to the pressure, with Arm caught in the AI selloff while its CEO, Rene Haas, has reportedly emerged as a contender to replace Huang, according to the Financial Times. Between earnings, export restrictions and the search for Nvidia’s next CEO, investors have plenty to digest, with tonight’s results likely to set the tone for the AI trade.
Ahead of Anthropic’s IPO this week, the performance of recent U.S. listings offers some food for thought. According to Financial Times analysis, shares of Wall Street’s 10 largest IPOs this year have fallen an average of -20.5% from their offering prices, despite 2026 being the busiest year for IPOs by deal value this decade. By comparison, the 10 largest IPOs in each of the previous four years finished their respective years with gains, even in 2022 when the S&P 500 fell -19.4%. Heavy equity issuance, elevated valuations and questions about returns on AI investment have weighed on post-IPO performance. Anthropic, which could command a valuation of up to $1.4 trillion, has attracted strong initial demand, but that has not necessarily translated into sustained gains for other recent listings. While the performance of this year’s IPO class is hardly an unbiased predictor of what lies ahead, it offers a useful temperature check as one of the most anticipated listings of the year approaches.
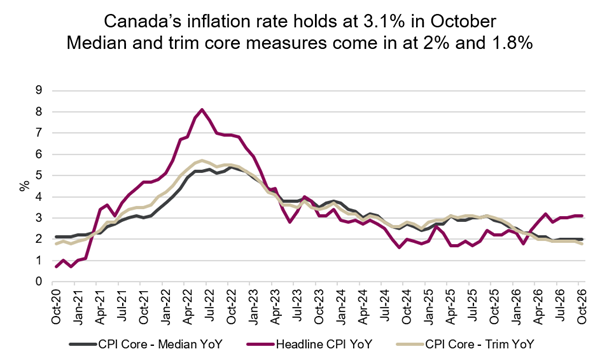
Loonie under pressure. Canada’s annual inflation rate held at 3.1% in October, slightly below expectations of 3.2%, as higher energy prices continued to put upward pressure on the headline reading. However, underlying inflation showed further signs of moderation, with the Bank of Canada’s preferred median and trim measures easing to 2% and 1.8%, respectively, while inflation excluding food and energy slowed to 1.8% from 2.1%. Grocery inflation edged higher to 2%, while rent inflation slowed to 1.7% from 2.8% in September. The softer reading offered some reassurance that higher energy costs have yet to spill over into broader consumer prices, especially as the economy contends with weaker employment and slower growth. The Canadian dollar briefly touched its lowest level against the U.S. dollar since April 2025, while the two-year Government of Canada bond yield fell ~5 basis points. Markets lowered the probability of another Bank of Canada rate hike in December to 50% from 60% before the release, suggesting the central bank may have more room to hold rates despite elevated headline inflation.
The U.S. is moving to shut the back door on China’s access to advanced U.S. AI chips, targeting a loophole that allowed Chinese companies to access computing power remotely through data centres in other countries. New rules would require operators in Singapore, Malaysia, Thailand, Indonesia and Brazil to obtain U.S. government licences for certain shipments of advanced AI chips, including those made by Nvidia. The announcement follows heightened scrutiny of Nvidia’s export practices after Jensen Huang’s resignation, as U.S. officials investigate whether intermediaries helped circumvent existing restrictions. Southeast Asia has become a hub for AI data centres, supported in part by demand from Chinese technology companies. The new measures could complicate Nvidia’s international sales and add another layer of uncertainty ahead of today’s earnings.
This comes ahead of a meeting between Donald Trump, Xi Jinping, and Vladimir Putin in Shenzhen on Thursday during the APEC summit. While the meeting is sure to be a great photo op, analysts expect limited progress on major issues, including the wars in Ukraine and Iran, nuclear arms control, and international security. For Russia, the summit is as an opportunity to reinforce its position as a global power, while China can demonstrate its diplomatic influence. The meeting, however, is raising concerns among European and Asian allies, including Ukraine, Japan, South Korea, and Taiwan, about the possibility of major powers negotiating arrangements that impact smaller countries without their involvement. Canada is also making moves at the summit, announcing additional trade measures with China aimed at strengthening economic ties. China will now remove its 25% tariff on $400 mln in annual Canadian exports, including frozen pork, shrimp, and some seafood products. In exchange, Canada will expand tariff exemptions to 32 additional Chinese steel and aluminum products where domestic supply is limited or unavailable. The countries also agreed to improve Chinese market access for some Canadian products and work towards more agricultural agreements. While the recent announcement may seem immaterial, it’s another small step towards co-operation, with Canadian exports to China having already increased 40% since Carney’s last visit to China in January.
The Democrats’ victory in the U.S. midterm elections could create a more favourable environment for Treasuries by reducing inflationary pressures and strengthening Fed independence. With Dems gaining control of both the House and Senate, some expect more opposition to tariffs, the Iran war, restrictive immigration policies, and the expansion of AI data centres. These could help ease supply-side inflation through lower energy prices, reduced trade costs, improved labour availability, and slower growth in electricity demand. Democratic control of the Senate should also limit Trump’s ability to appoint politically aligned Fed officials, helping preserve monetary policy independence and anchor long-term inflation expectations. Still, fiscal policy is a big question mark, with the U.S. budget deficit remaining near 6% of GDP, and upcoming debt ceiling negotiations in March potentially leading to a spending agreement that increases deficits through expanded social programs, defence spending, or tax extensions.
Shaken, not stirred. Robert Pattinson has been named as the next James Bond (agree to disagree on that one), succeeding Daniel Craig and becoming the seventh actor to play the British spy. The announcement was made through the franchise’s social media channels, with Canadian director Denis Villeneuve set to direct the 26th Bond film. The upcoming movie will be a transition for the franchise, becoming the first instalment since Amazon MGM Studios assumed creative control last year. The last Bond film, No Time to Die, was released in 2021 and earned more than $750 mln globally, concluding Craig’s five-film tenure. Of course, casting the next 007 was never going to please everyone, and Pattinson’s selection is sure to stir up some debate. Whether he can fill Craig’s shoes remains to be seen, but who’s your favourite Bond? Connery, Moore, Brosnan, Craig or someone else?
Diversion: Put more into the celebration than the tackle