Launch Pad

Stay on top of market movements with the Launch Pad. Updated daily.

November 16, 2026
  
Click here to sign up for the Launch Pad
     
Today

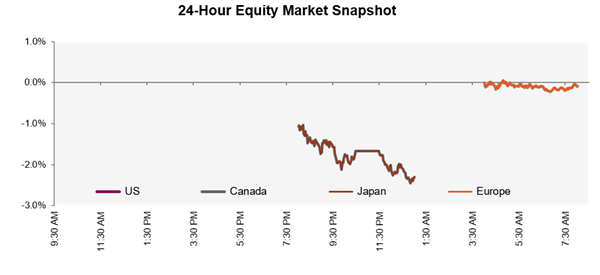
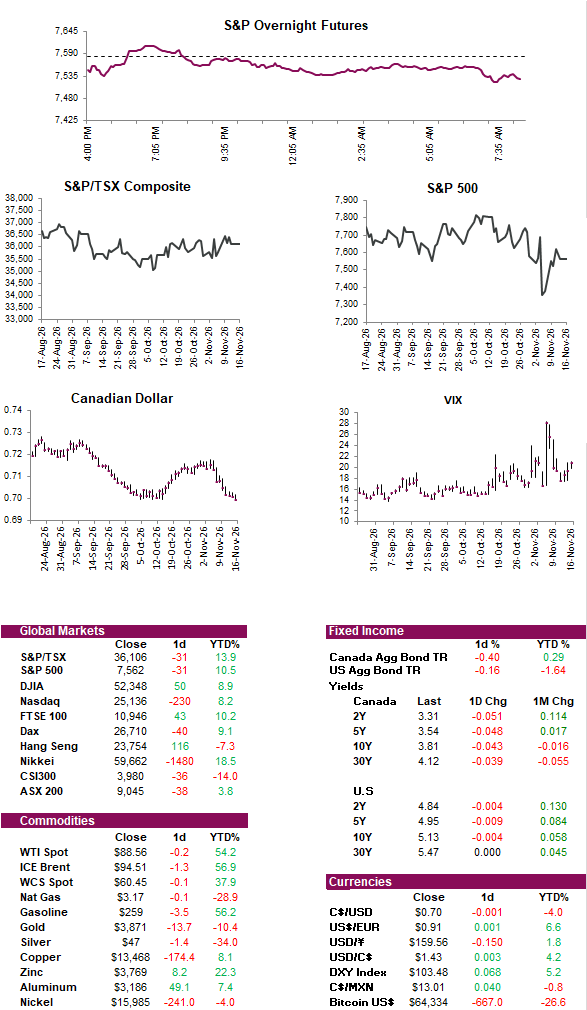
The fallout from Nvidia continues, with shares down -3% at the time of writing. By Friday’s close, the company’s market cap had fallen to $3.9 trillion from a peak of $5.8 trillion, wiping out $1.9 trillion in value, or ~32%. Two major tests await the AI trade this week, starting with Nvidia’s earnings tomorrow, followed by Anthropic’s IPO, which is expected to price Wednesday and begin trading Thursday. Nvidia may deliver another strong quarter, but investors will be looking beyond the numbers as interim CEO Colette Kress, previously the company’s CFO, takes the helm following Jensen Huang’s resignation. Huang transformed Nvidia from a gaming chipmaker into the dominant supplier of AI computing infrastructure, making his departure more than a conventional leadership change. The challenge for investors is determining how much of Nvidia’s valuation depended on Huang and whether the company can maintain its technological lead, customer relationships and growth trajectory without him. Given Nvidia’s central role in the AI infrastructure buildout, the implications extend beyond the company itself. Meanwhile, Anthropic is targeting a valuation of at least $1.3 trillion, a significant test of investor appetite at a time when AI valuations, capital spending and the eventual returns on those investments are facing greater scrutiny. The timing is hardly ideal, with Nasdaq futures down -1.3% this morning as technology shares face further selling pressure.

Taking a look under the hood. The recent selloff in AI-related stocks is prompting investors to reassess their true exposure to AI, as concerns grow over elevated valuations, slowing capital spending, and increasing market concentration. According to MSCI, at least $25.3 tln is invested in companies with direct AI exposure, although that doesn’t include indirect exposure across sectors such as utilities, industrials, healthcare, and credit markets, which is harder to quantify. Recent research found that 52 AI-related companies accounted for 38.5% of public equity holdings among a group of large pension funds as of June 2026, up from 20.7% in 2010, highlighting the rising concentration risk. Asset managers are now conducting more detailed assessments of both direct and indirect AI exposure across their portfolios, including potential vulnerabilities to a slowdown in data centre investment. This comes as investors become more selective, recognizing that AI-driven productivity improvements may not translate into higher corporate profitability. 

Canada is looking to build stronger trade and investment ties with China as part of its strategy to reduce reliance on the U.S. Officials have emphasized several opportunities for collaboration while noting that safeguards around foreign investment and national security, need to also be in place. Potential areas of cooperation include consumer goods, financial services, banking, renewable energy, and battery storage technology, where China currently has the competitive advantages. Ottawa is aiming to double exports to markets outside the U.S. by 2035 and increase exports to China by 50%, with a focus on helping Canadian small- and medium-sized businesses access Chinese consumers through platforms like Alibaba. Canada has also extended an agreement providing lower tariffs on agricultural exports through 2028, building on an earlier arrangement allowing up to 49,000 Chinese electric vehicles into Canada annually at tariffs of 6%. Mark Carney is scheduled to meet with Xi Jinping later this month, where additional trade and investment initiatives are expected to be announced. 

Get it while you can! Retailers are expected to carry lower inventories of big-ticket holiday items, including TVs, appliances, and grills. This comes amid rising transportation, fuel, and inventory financing costs pressure supply chains, with trucking rates increasing +47% y/y in early November, while fuel surcharges rose 64%. Adding to this, elevated yields have increased inventory carrying costs, encouraging retailers to limit excess stock and adopt cautious purchasing strategies. Retailers are balancing higher shipping costs against the risk of product shortages, with some executives anticipating bigger sales closer to the holidays as companies look to clear remaining inventory. Despite these pressures, U.S. holiday retail sales are expected to exceed $1 trillion this year, although higher prices, rather than stronger consumer demand alone, are contributing to the increase. 

Cleared for an upgrade. Airlines in the U.S. are working to restore normal operations following the country’s longest nationwide aviation shutdown in more than two decades. The ordeal resulted in over 17,000 flight cancellations and widespread delays, with over 10,000 flights still delayed, although major carriers expect operations to normalize today. The disruption has been linked to a network overload during the replacement of outdated copper wiring in Arkansas, with equipment operated by L3Harris Technologies under investigation, although the specific cause remains uncertain. The episode highlights the vulnerabilities in U.S. aviation infrastructure, with the administration now seeking $50 billion to modernize the country’s aging air traffic control system. Apparently, bringing air traffic control into the 21st century is proving harder, and more expensive, than expected. 

Edmonton is seeing green. It wasn’t the Oilers, but Edmonton has plenty to celebrate this morning. The Elks defeated the Montreal Alouettes 37-30 on Sunday to capture their 15th Grey Cup and end an 11-year championship drought. QB Cody Fajardo earned MVP honours with two passing touchdowns and two rushing scores, leading a turnaround for a franchise that was struggling both on and off the field. Just a few years ago, the Elks had a 22-game home losing streak, declining attendance and financial losses that threatened the team’s future. New ownership in 2024 helped stabilize the franchise, while changes in management and coaching paid off. After finishing last in the West Division a year ago, Edmonton posted a 13-5 record this season, secured its first home playoff game since 2015 and capped its comeback with a championship victory in Calgary. For a city accustomed to pinning its championship hopes on McDavid and the Oilers, it’s nice to see another team bring home some hardware.


Diversion: It’s good to have a little fear 

 
The
Tactical model 
(% equity weight)

Company news

Canadian Natural Resources has agreed to acquire Advantage Energy for $2.255 bln, or $13.55 per share, representing a 25% premium to Friday’s closing price, as consolidation continues across Canada’s oil and gas sector. The transaction has a total enterprise value of $2.53 bln, including Advantage’s net debt and outstanding convertible debentures, and is expected to close in the first quarter of 2027. The acquisition will expand Canadian Natural’s oil and gas production in Alberta while helping improve efficiencies. The deal comes amid elevated energy prices alongside a more supportive domestic policy environment for Canadian energy investment and infrastructure development. It also follows several major industry transactions, including Strathcona Resources’ proposed $2.9 bln acquisition of Greenfire Resources and Cenovus Energy’s $5.8 bln purchase of Athabasca Oil.

Nvidia is facing political and regulatory pressure following Jensen Huang’s removal as CEO, with U.S. Treasury Secretary Scott Bessent calling for a leadership overhaul and greater transparency regarding the company’s compliance with semiconductor export restrictions. Bessent has urged Nvidia’s board to appoint an external CEO and provide answers within 10 days regarding allegations that advanced AI chips were improperly diverted to China through intermediaries. It won’t be an easy start for interim CEO Colette Kress, who is expected to face scrutiny when Nvidia reports quarterly earnings tomorrow. 

Canaccord Genuity Group has agreed to sell its UK wealth management business to Centerbridge Partners and Abu Dhabi-based Mubadala Investment Company, paving the way for management to take the firm private. The UK division is being sold at an enterprise valuation of £1.17 bln, with Canaccord expected to receive £564 mln in proceeds that will help finance the management-led buyout. Under the proposed transactions, shareholders would receive $15.27 per share in cash, consisting of $7.45 for the remaining business and the Canadian-dollar equivalent of £4.15 from the UK sale. The agreement includes a 45-day period to solicit competing offers, while shareholders representing 35% of outstanding shares, including shares issuable upon conversion of convertible debentures, have indicated their support. 

Nike is facing growing investor skepticism ahead of its first investor day in nearly a decade, as management attempts to outline a turnaround strategy following several years of declining sales and market share losses. The company recently announced its third round of cost reductions this year, targeting $2.5 bln in savings over five years through layoffs, geographic consolidation, and a smaller logistics footprint. However, investors remain more focused on restoring revenue growth through innovative footwear and apparel that can compete with competitors while reducing reliance on discounting. Nike’s sportswear and Jordan divisions, which account for nearly half of its business, continue to struggle with weak demand and excess inventory, while China remains a significant challenge. Nike’s new CEO, Elliott Hill, hasn’t been able to demonstrate a sustained recovery since taking over two years ago, with Nike shares losing more than half their value during his tenure. Investors are also concerned that aggressive cost reductions could negatively affect customer experience, particularly through longer delivery times. 


Commodities

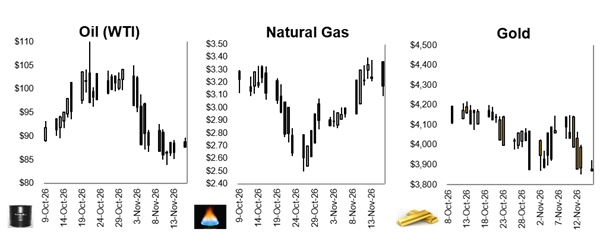
Oil prices declined despite renewed Iranian attacks on Bahrain and shipping near the Strait of Hormuz, as improving supply conditions outweighed geopolitical risks. Brent slipped toward $95 a barrel, while WTI traded near $88. The IEA estimates global supply is exceeding demand by roughly 2 million barrels per day this quarter, supported by recovering Middle Eastern production. Saudi Arabia has boosted output and cut selling prices, adding pressure on crude. However, refined fuel markets remain tighter, particularly diesel, as refinery disruptions and winter heating demand continue to support prices. Looking ahead, Goldman Sachs expects a sizeable oil surplus of 2 million barrels per day in 2027, even after accounting for potential supply disruptions. The bank forecasts Brent averaging $88 a barrel next year before declining to $78 by year-end as geopolitical risk premiums ease. Goldman also expects China’s oil demand to have peaked in 2025, with persistent weakness in road-fuel consumption weighing on global demand. The outlook suggests further downside for crude prices, although renewed supply disruptions remain a key risk.

Gold stabilized near $3,890 an ounce after falling -4.6% last week, its worst weekly decline since June. Stronger-than-expected U.S. inflation and hawkish Fed commentary increased expectations for further rate hikes in 2027, pushing two-year Treasury yields up 33 basis points and the 10-year yield above 5%. Higher yields weighed on the non-interest-bearing metal, with investors now looking to Fed officials and the October meeting minutes for further policy guidance. 


Fixed income and economics

Japan’s economy contracted by an annualized -0.1% in Q3, following 1.7% growth in Q2, as weak consumer spending and exports weighed on activity. Much of the weakness was attributed to temporary factors, including severe weather and an earthquake that disrupted manufacturing. Private consumption fell 0.3% for a second consecutive quarter, while net exports subtracted 2.4 percentage points from growth. Business investment provided a bright spot, rising 1.6%, suggesting higher interest rates have yet to materially constrain corporate spending. Economists expect the Bank of Japan to look through the GDP weakness and proceed with a 25-basis-point rate hike in December, followed by further increases in March and July, bringing the policy rate to 2%. The main risk to this outlook is persistent weakness in household consumption as inflation accelerates and the weaker yen erodes purchasing power.

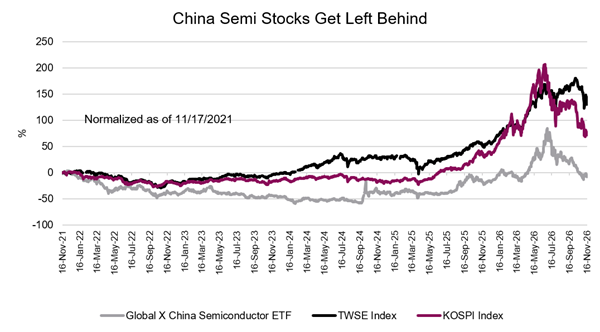
Meanwhile, China’s economy showed further signs of weakness in October, with consumer spending, industrial production and investment all falling short of expectations despite Beijing’s recent stimulus measures. Retail sales rose just 0.4% y/y, while industrial output growth slowed to 4.8%. Fixed-asset investment fell -8.1% in the first ten months of the year, weighed down by a property downturn, with real estate investment plunging -21.6%. The weakness highlights China’s continued reliance on exports, which accounted for nearly 40% of GDP growth in Q3. With domestic demand struggling and uncertainty surrounding global demand for AI-related goods, pressure is building for additional fiscal stimulus. Attention now turns to Beijing’s December economic policy meeting for clues on further support and priorities for 2027. 


Chart of the day
 

Markets

Quote of the day
 

We may encounter many defeats but we must not be defeated. 

Maya Angelou 

Contributors: A. Innis, A. Nguyen, P. Kwon

Charts are sourced to Bloomberg unless otherwise noted.

The opinions expressed in this report are the opinions of the author and readers should not assume they reflect the opinions or recommendations of Richardson Wealth Limited or its affiliates. Assumptions, opinions and estimates constitute the author’s judgment as of the date of this material and are subject to change without notice. We do not warrant the completeness or accuracy of this material, and it should not be relied upon as such. Before acting on any recommendation, you should consider whether it is suitable for your particular circumstances and, if necessary, seek professional advice. Past performance is not indicative of future results. Richardson Wealth Limited is a subsidiary of iA Financial Corporation Inc. and is not affiliated with James Richardson & Sons, Limited. Richardson Wealth is a trade-mark of James Richardson & Sons, Limited and Richardson Wealth Limited is a licensed user of the mark. Richardson Wealth Limited, Member Canadian Investor Protection Fund.

Related articles

Market Ethos

Drowning out the political noise

9 November 2026. Market Ethos. It appears the size of the blue wave defused a number of risks, and markets reacted positively for a day.…

23 minute read

Estate planning

2026 Federal Budget

Following significant trade uncertainty in recent times, Budget 2026, titled “Masters of our Destiny”, follows themes of strengthening foundations in Canada, diversifying trade partnerships, and…

23 minute read

Investor Strategy

Stickhandling the headwinds

3 November 2026. Investor Strategy. While November and December are often positive months, they may prove to be challenging this year. It has been a…

23 minute read