Sign up here to receive the Market Ethos by email.
The inflation spike in 2021 and 2022 remains pretty fresh in investors’ minds. Recall how most were convinced it would simply be ‘transitory’, driven by the abrupt stop and start of the global economy due to COVID? Instead, core inflation in both Canada and the U.S. rose to a 6-7% pace before coming back down over the past few years. With the benefit of hindsight, this spike was logical: we shut down the economy, everyone stopped spending, then reopened it up to a populace with excess savings and accumulated pent-up demand to do stuff. And that stuff didn’t necessarily mean going back to work. Prices spiked and wage growth rose to try luring workers back.
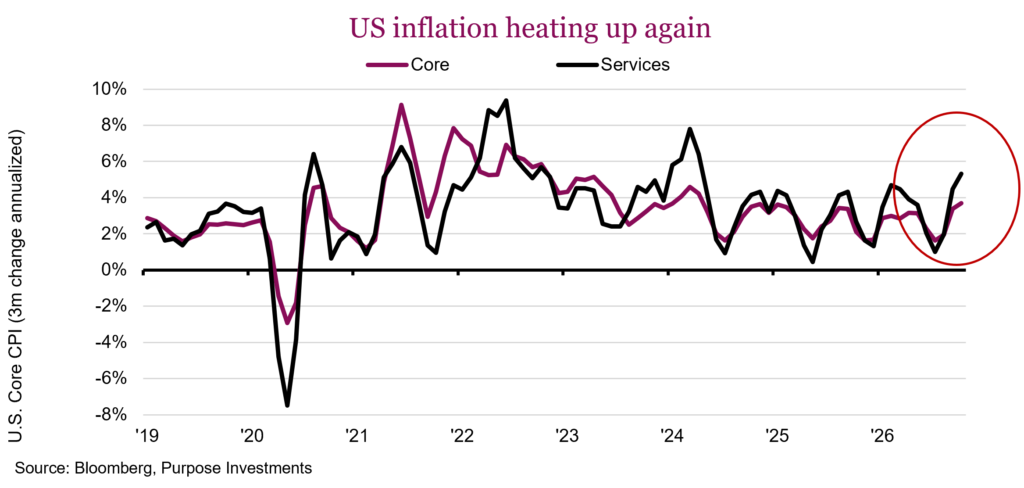
Then again, inflation is a very slow process so perhaps a two-year spike is transitory after all. It’s just that in our current society’s mental model, with shorter attention spans, anything that lasts longer than a couple weeks is now labelled a secular trend. More pertinent, there has been a recent uptick of inflation data raising some alarm bells. To get a better idea of the inflation pace, we will first turn to the 3-month annualized pace instead of the more often quoted year-over-year. It simply reacts more quickly, which makes it more useful.
There is a bit more inflation risk that has been building. Globally, we have seen a mild uptick, similar to the U.S. Of course, elevated energy prices are a big contributor. While that doesn’t directly impact core inflation data, it does so indirectly. And the longer energy prices remain elevated, the more the impact grows. Many other commodity prices are up as well, including copper. On the demand side, the growth in global manufacturing has certainly contributed to higher input prices, and that will impact end prices. Even China, often an exporter of deflationary pressure, doesn’t seem to be doing so anymore. China Producer Price Index is up 5.7%, certainly on the historical high side.
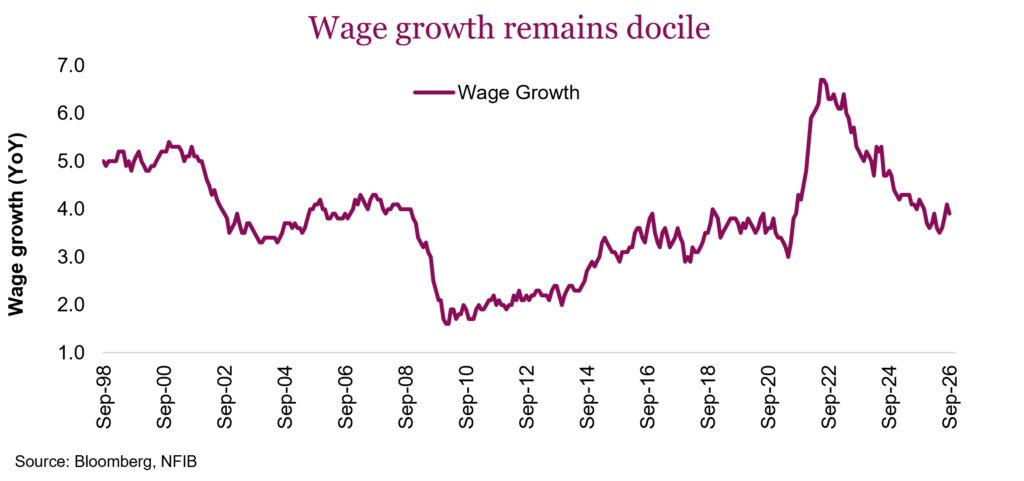
Some inflation does make sense and shouldn’t be too alarming. It would be natural to have some inflation, given a global economy that is doing well and strong investment demand building data centers. AI should help productivity over time and will ease inflation pressures. But the building of the AI infrastructure is certainly inflationary. We would become more worried if wages started to rise or if inflation break evens turned up. So far these factors are muted.
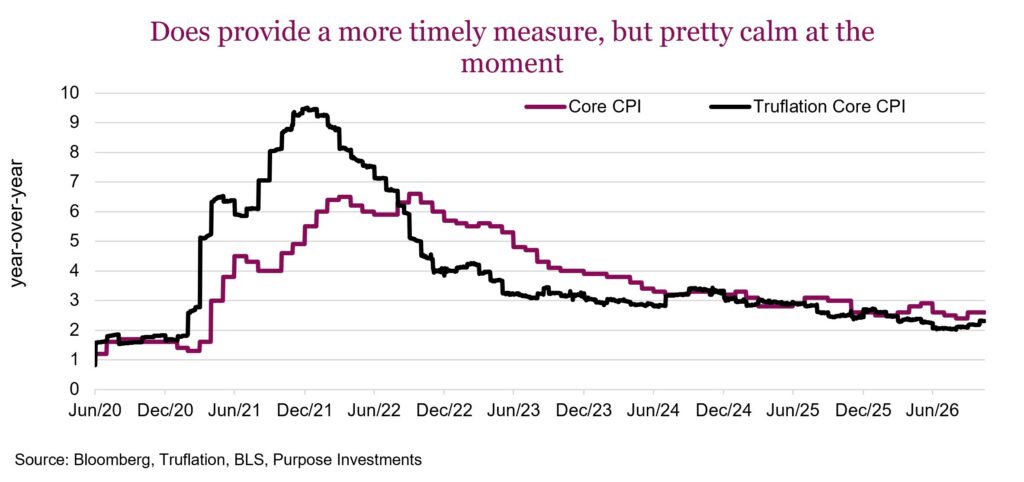
Let’s turn to some alternative data. Consumer Price Index data comes from the U.S. Bureau of Labor Statistics and is calculated monthly across 75 urban areas from about 6,000 households and 22,000 establishments. Housing is based on owner-occupied rent, which has a pretty big weight and is often subject to some skepticism. There are also adjustments for improvements and substitutes. It is quality work with a very thoughtful process that has evolved over decades. But we do now live in a data-rich world, and there are rising alternative sources. Truflation is a private data provider that amalgamates daily prices across an estimated 15 million items.
We are not saying one is better than the other, only that they are different, which has benefits and drawbacks. Using alternative data to support or refute trends in the more popular government data is the difference between taking the guided tour and digging deeper. So far, we are not seeing any rise that would get us overly worried on the inflation front.
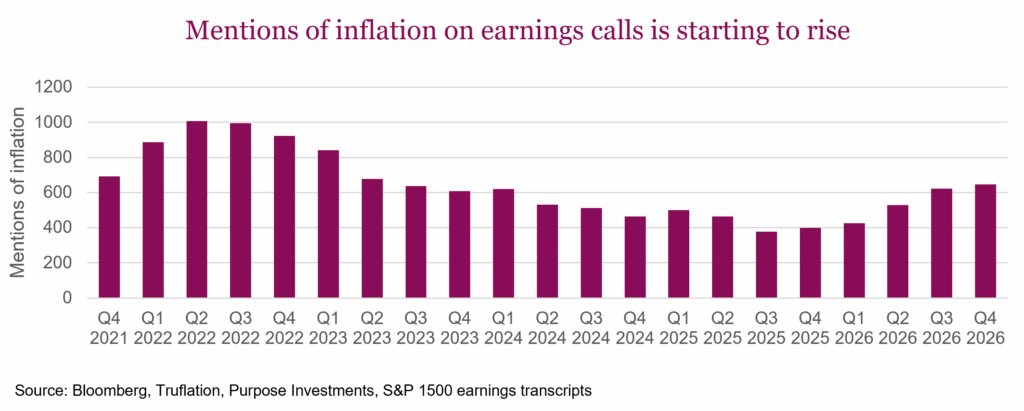
Another alternative data source is at the company level. The following chart measures the frequency of companies talking about inflation during earnings conference calls. While this has risen somewhat, it remains well below levels seen heading into the inflation spike of 2022.
Final thoughts
Taken in totality, inflation risk has risen a bit over the past few months. If these trends continue to build in the coming months or quarters, we will become more worried. For now, however, we remain in the camp that inflation is not high on our list of things to worry about. But it has risen enough to warrant some inflation protection within portfolios. This can take the form of real assets or cyclical equities that often benefit from rising inflation.
Source: Charts are sourced to Bloomberg L.P., Purpose Investments Inc., and Richardson Wealth unless otherwise noted.
The contents of this publication were researched, written and produced by Purpose Investments Inc. and are used by Richardson Wealth Limited for information purposes only.
*This report is authored by Craig Basinger, Chief Market Strategist at Purpose Investments Inc. Effective September 1, 2021, Craig Basinger has transitioned to Purpose Investments Inc.
Disclaimers
Richardson Wealth Limited
The opinions expressed in this report are the opinions of the author and readers should not assume they reflect the opinions or recommendations of Richardson Wealth Limited or its affiliates. Assumptions, opinions and estimates constitute the author’s judgment as of the date of this material and are subject to change without notice. We do not warrant the completeness or accuracy of this material, and it should not be relied upon as such. Before acting on any recommendation, you should consider whether it is suitable for your particular circumstances and, if necessary, seek professional advice. Past performance is not indicative of future results. The comments contained herein are general in nature and are not intended to be, nor should be construed to be, legal or tax advice to any particular individual. Accordingly, individuals should consult their own legal or tax advisors for advice with respect to the tax consequences to them.
Purpose Investments Inc.
Purpose Investments Inc. is a registered securities entity. Commissions, trailing commissions, management fees and expenses all may be associated with investment funds. Please read the prospectus before investing. If the securities are purchased or sold on a stock exchange, you may pay more or receive less than the current net asset value. Investment funds are not guaranteed, their values change frequently and past performance may not be repeated.
Forward Looking Statements
Forward-looking statements are based on current expectations, estimates, forecasts and projections based on beliefs and assumptions made by author. These statements involve risks and uncertainties and are not guarantees of future performance or results and no assurance can be given that these estimates and expectations will prove to have been correct, and actual outcomes and results may differ materially from what is expressed, implied or projected in such forward-looking statements. Assumptions, opinions and estimates constitute the author’s judgment as of the date of this material and are subject to change without notice. Neither Purpose Investments nor Richardson Wealth warrant the completeness or accuracy of this material, and it should not be relied upon as such. Before acting on any recommendation, you should consider whether it is suitable for your particular circumstances and, if necessary, seek professional advice. Past performance is not indicative of future results. These estimates and expectations involve risks and uncertainties and are not guarantees of future performance or results and no assurance can be given that these estimates and expectations will prove to have been correct, and actual outcomes and results may differ materially from what is expressed, implied or projected in such forward-looking statements. Unless required by applicable law, it is not undertaken, and specifically disclaimed, that there is any intention or obligation to update or revise the forward-looking statements, whether as a result of new information, future events or otherwise.
Before acting on any recommendation, you should consider whether it is suitable for your particular circumstances and, if necessary, seek professional advice.
The particulars contained herein were obtained from sources which we believe are reliable but are not guaranteed by us and may be incomplete. This is not an official publication or research report of either Richardson Wealth or Purpose Investments, and this is not to be used as a solicitation in any jurisdiction.
This document is not for public distribution, is for informational purposes only, and is not being delivered to you in the context of an offering of any securities, nor is it a recommendation or solicitation to buy, hold or sell any security.
Richardson Wealth Limited is a subsidiary of iA Financial Corporation Inc. and is not affiliated with James Richardson & Sons, Limited. Richardson Wealth is a trade-mark of James Richardson & Sons, Limited and Richardson Wealth Limited is a licensed user of the mark. Richardson Wealth Limited, Member Canadian Investor Protection Fund.
Related articles
Market Ethos
Drowning out the political noise
9 November 2026. Market Ethos. It appears the size of the blue wave defused a number of risks, and markets reacted positively for a day.…